Knowledge for the Road Ahead
Most drivers understand miles, maintenance, and protecting equipment. This section was created to explain financial protection concepts in simple language — through real-world inspired trucking scenarios.
Built for Drivers. Designed for Real Conversations.
Many drivers were never shown how financial protection products can also become part of a long-term strategy for protecting their family, business, income, and future goals.
These examples are educational only and designed to help owner-operators and drivers better understand the different types of protection and planning strategies available. All scenarios are fictional and for illustrative purposes only.
Term life insurance provides coverage for a defined period of time — often 10, 20, or 30 years. For drivers in their peak earning years with families depending on their income, it can be a straightforward way to create a financial safety net.
Whole life insurance provides lifelong coverage and builds cash value over time at a guaranteed rate. For drivers thinking long-term, it can serve as both a protection strategy and a stable financial asset.
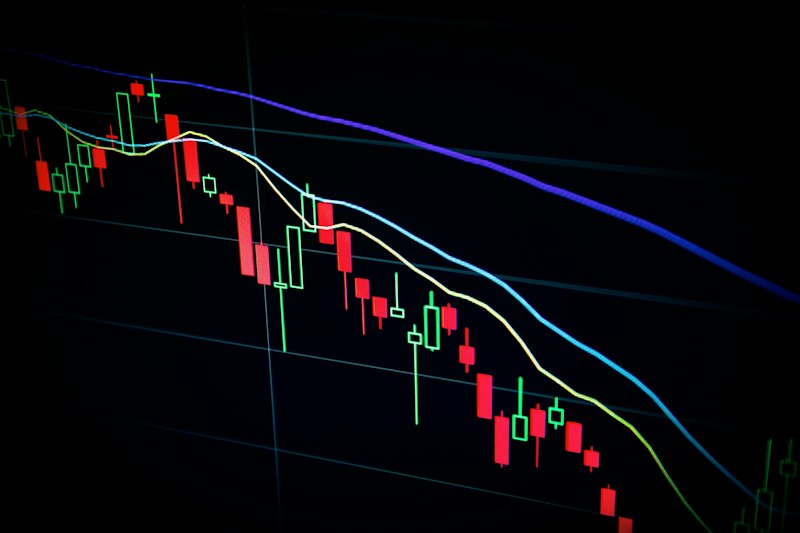
Indexed Universal Life (IUL) is a type of permanent life insurance that offers flexible premiums and death benefit, with cash value growth linked to a market index — subject to caps and floors. It may appeal to drivers looking for both protection and long-term accumulation potential.
A Fixed Indexed Annuity (FIA) is a contract with an insurance company designed for retirement savings. It offers the potential for interest credits linked to a market index, while protecting principal from direct market losses. FIAs are not investments and do not directly participate in the stock market.
Final expense insurance is typically a smaller whole life policy designed to help cover end-of-life costs such as funeral and burial expenses. It can help reduce the financial burden placed on family members during an already difficult time.
Some financial products — particularly certain types of permanent life insurance — may offer accessible cash value that can serve as a financial buffer during unexpected events. This is not a substitute for a dedicated emergency fund, but may complement an overall financial strategy.
Business continuity planning for owner-operators may involve a range of strategies — from key-person life insurance to buy-sell agreements funded by life insurance. These strategies are designed to help protect the business and its stakeholders in the event of an unexpected loss.
These educational examples are fictional scenarios created for illustrative purposes only. Insurance products, policy features, benefits, guarantees, costs, loan availability, and financial outcomes vary by carrier, policy structure, underwriting approval, state regulations, and individual circumstances.
Loans and withdrawals may reduce policy values and benefits. Fixed Indexed Annuities are not securities and do not directly participate in the stock market. IUL cash value growth is subject to caps, participation rates, and policy charges.
This content is for educational purposes only and should not be interpreted as financial, tax, legal, or investment advice. Please consult a licensed professional regarding your individual situation.
Ready for a Real Conversation?
These concepts are a starting point. A licensed professional can help you understand what strategies may fit your specific situation, goals, and budget.